

 Breaking News
 Krishani
 Krishani
 Oct 30 2026
 38
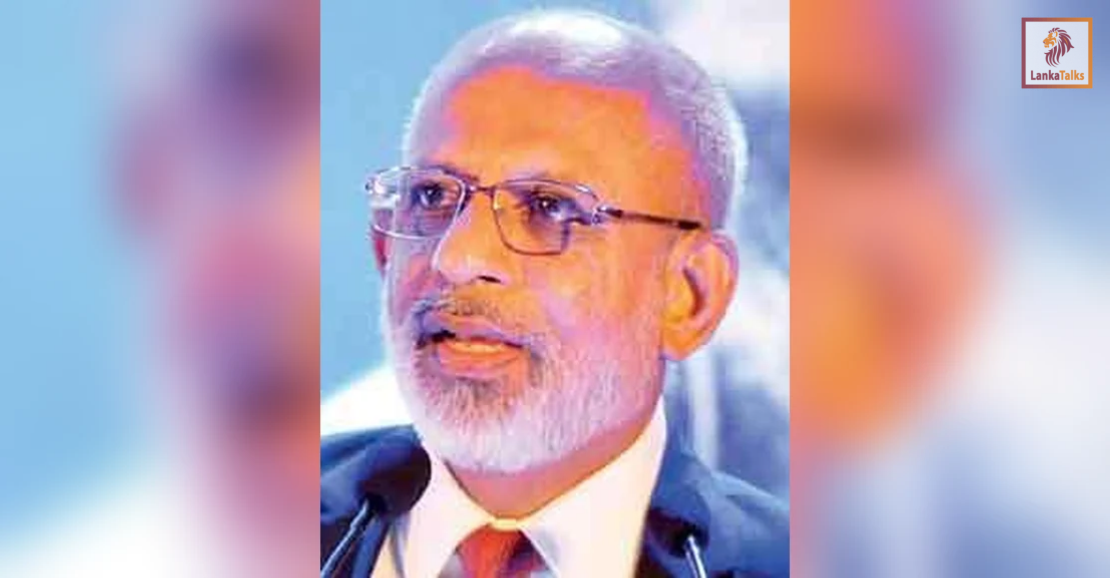
Addressing the Capital Market Industry Forum on October 27, Dissabandara said economic stabilisation had laid the foundation for recovery, but the next challenge was to mobilise investment that raises productivity, builds competitive enterprises, expands exports and creates employment.
He described recent growth of approximately 4–5 percent as encouraging following the economic crisis, while arguing that Sri Lanka should aspire to a sustained trajectory of 7–9 percent, supported by improvements in productivity, competitiveness and investment.
“We cannot simply announce a higher growth target and expect the economy to achieve it,” he said.
Policymakers must first establish how much additional investment is required, identify sectors offering the greatest potential for productivity gains, value addition, exports and employment, and determine how that investment can be financed.
“We cannot sustainably achieve higher growth by depending excessively on Government borrowing. Nor should the banking sector alone be expected to provide every form of financing required by a modern, expanding economy.”
While banks remained essential for working capital, business operations and conventional lending, long-term productive investments required financing instruments suited to their duration and financial requirements, he said.
Dissabandara distinguished between economic rescue, recovery and sustainable growth, warning against treating progress in stabilisation as the completion of Sri Lanka’s economic adjustment.
Debt restructuring, the IMF-supported programme and fiscal and monetary reforms had provided an important foundation, he said, pointing to progress in fiscal consolidation, external finances, exchange-rate management and economic confidence.
“But we must understand that economic rescue is not the same as economic recovery, and economic recovery is certainly not the same as sustainable economic growth.”
Although maintaining macroeconomic stability and completing reforms remained necessary, he argued that the country’s ambitions must extend beyond managing existing obligations or depending indefinitely on external financial assistance.
Sri Lanka needed to generate its own productive capacity, attract investment and improve living standards, supported by financial discipline, institutional accountability and sound economic systems.
Dissabandara said Sri Lanka had insufficiently used its capital market throughout much of its post-Independence development, with financing discussions concentrating heavily on government borrowing, commercial banking and external debt.
The country already possessed a stock exchange, market intermediaries, investment management institutions and a regulatory framework through which long-term capital could be mobilised, he noted.
“The capital market is not merely a place where investors buy and sell shares. It is a mechanism for capital formation, resource mobilization and the allocation of savings towards productive investment.”
Equity financing could enable businesses to raise funds without the same fixed repayment obligations associated with conventional borrowing, while corporate debt markets could provide longer-term funding matched to companies’ requirements.
Collective investment schemes could give smaller savers access to diversified investments, while new financial products could direct funds towards infrastructure, sustainable energy, industrial development and entrepreneurship.
“What Sri Lanka needs today is not simply more money circulating within the economy. We need more capital being directed towards investments that create lasting economic value.”
Greater use of public markets could also strengthen corporate governance, transparency, financial reporting and investment discipline, he said. Businesses seeking public funds must demonstrate their credibility, financial performance and prospects, while investors assess where to allocate their savings.
He urged companies and entrepreneurs to show greater willingness to use capital market financing to expand productive activities.
The forthcoming Budget offered an opportunity to translate that approach into policy, Dissabandara said, calling for serious consideration of proposals identified by the SEC and Colombo Stock Exchange (CSE).
He advocated measures to encourage capital raising and new listings, facilitate appropriate financial instruments, attract long-term institutional investors and broaden public participation. The speech did not detail the individual Budget proposals.
Suitable state-owned enterprises could also be considered for capital market participation, subject to government policy, commercial viability, public interest and appropriate governance arrangements.
Policy consistency would be essential to attracting long-term commitments, he said, as investors assess institutional credibility and the stability of the policy environment alongside economic prospects.
Dissabandara outlined a development agenda comprising 12 projects under the SEC’s Capital Market Strategy for 2025 –2035, intended to strengthen both capital formation and market infrastructure.
The agenda includes developing corporate debt, introducing products, expanding collective investment schemes, encouraging listings and attracting additional domestic and foreign investment.
Infrastructure initiatives include the demutualisation of the CSE, a central counterparty mechanism and the development of a multi-asset-class derivatives exchange. Other priorities include investor education, research and training, regulatory development, digital transformation and risk management.
Some initiatives could deliver benefits relatively quickly, while others required substantial institutional preparation, consultation, technological investment and legislative or regulatory development, he said.
“Regulation is indispensable. Without effective regulation, investor protection, market integrity and confidence cannot be sustained. But regulation alone cannot create a dynamic capital market.”
The regulator also needed to facilitate innovation and enable legitimate businesses and investors to participate efficiently, he said.
The strategy must anticipate changing investor expectations, including digital accessibility, technology-driven investment services and new instruments, while addressing cybersecurity, data protection and the responsible use of artificial intelligence.
Turning to the recent decline in share prices, Dissabandara urged investors to assess risks objectively and avoid panic-driven decisions.
In his assessment, the market had been affected by a combination of Middle East geopolitical developments, higher international energy prices, foreign portfolio adjustments, changes in interest rates, inflationary pressures, exchange-rate movements, profit-taking and periods of low liquidity.
Some companies faced pressure on operating costs and profitability, but he cautioned against interpreting a broad market decline as evidence that every listed business had become fundamentally weak.
Foreign equity outflows should also be assessed alongside wider capital movements, he said, pointing to foreign investment inflows into government securities.
He cautioned that weak sentiment and low liquidity could amplify selling pressure, with profit-taking, margin calls and changing expectations reinforcing price movements.
“When liquidity is low and investor sentiment is weak, even relatively modest selling pressure can produce significant price movements.”
Investors needed to distinguish genuine economic risks from rumours, and temporary price fluctuations from lasting changes in the underlying value of businesses, he said.
His presentation examined market performance from 1985 to October 2026, emphasising that investment returns should be assessed over an appropriate period and account for dividends, inflation and risk, rather than index movements alone.
He stressed that historical equity returns had been accompanied by substantial volatility, and that additional returns were neither guaranteed nor evenly distributed across years.
Dissabandara also warned that thin trading required greater attention to market integrity, as attempts to influence prices or create misleading impressions of buying and selling could have a disproportionate effect when volumes were low.
The warning was particularly relevant ahead of important policy announcements, including the Budget, he said, while making clear that ordinary price declines and legitimate changes in expectations did not themselves constitute manipulation.
He identified no specific misconduct case or investigation in the speech, but said the regulatory framework was in place to address prohibited practices.
Market professionals also had responsibilities extending beyond legal compliance and transaction execution, he argued.
“We should not encourage clients to buy merely because prices are rising. Nor should we encourage them to sell simply because the market has declined.”
Stockbrokers, advisers and fund managers needed to assess company fundamentals, economic developments and emerging risks, while helping clients make decisions consistent with their financial circumstances.
Inappropriate advice, exaggerated predictions and unverified information could contribute to unnecessary panic, he warned.
“Investor confidence cannot be created through optimistic statements alone. It must be earned through competence, transparency, honesty and professional integrity.”
Dissabandara said the broader objective was to build a market capable of financing enterprises and productive investment, with policymakers, businesses, investors and intermediaries sharing responsibility for that transition.
“Our challenge is not merely to achieve a higher stock market index. Our challenge is to build a capital market that creates real economic value, supports enterprises, protects investors and contributes meaningfully to national prosperity.